Cost of Funding Research Report
Overview
The analysis compared the cost of funding implications for an investment grade issuer using four different debt portfolio issuance strategies.
Abstract: Currently, many institutions issue debt in the public markets on an episodic or “one-off” basis. This is driven in part by the existing primary bond issuance process imposing limitations on liquidity and issuance sizes (i.e. notional amount issued). In our analysis, we considered a state of the world where institutions have the ability to issue public market debt in (1) smaller issuance sizes and (2) on a more frequent basis. This would be analogous to how some large financial and government institutions currently issue debt in a scheduled fashion. Ultimately, we aimed to discover if there were any cost of debt implications to issuing bonds with a regular frequency, as opposed to episodically.
Data File: The data utilized includes all U.S. treasury rates and generic “BBB” index spreads from 2002 to 2016. In aggregate, there are over 7,000 unique data points.
Debt Portfolio Issuance Strategies
Portfolio 1
- Issuance Frequency: Bi-Annual
- Issuance Size: $2BN per issuance
- Issuance Tenor: 10 years
- Credit Rating: Generic BBB
Portfolio 2
- Issuance Frequency: Annual
- Issuance Size: $1BN per issuance
- Issuance Tenor: 10 years
- Credit Rating: Generic BBB
Portfolio 3
- Issuance Frequency: Quarterly
- Issuance Size: $250MM per issuance
- Issuance Tenor: 10 year
- Credit Rating: Generic BBB
Portfolio 4
- Issuance Frequency: Monthly
- Issuance Size: $83.33MM per issuance
- Issuance Tenor: 10 years
- Credit Rating: Generic BBB
Data Inputs & Assumptions
The analysis contains a few important assumptions that were made due to limited data availability and the primary bond issuance process.
Data Inputs
- U.S. 10-Year Treasury Rate: The benchmark interest rate for an investment grade U.S. Dollar bond issuance
- U.S. 10-Year Corporate Generic BBB Index: The credit spread over the U.S. treasury rate for a BBB rated issuer
- Data Time Series: September 30th, 2002 to September 29th, 2016
- Selected due to the U.S. 10-Year Corporate Generic BBB Index only being reported since September 30th, 2002
- Data Source: Pubic Sources
Assumptions
- The “hypothetical institution” had the ability to issue in the primary bond market on any market trading day
- The “hypothetical institution” had the ability to issue in any issuance size
- Data Time Series: September 30th, 2002 to September 29th, 2016
- The “hypothetical institution” issued exclusively in U.S. Dollars and for a 10-year tenor*
* Assumption 3 was made due to the 10-year generic “BBB” credit spread index having the largest historical data set that was a representative data set for the analysis
Modelling Methodology
Four unique debt portfolio structures were back tested and the average cost of debt on a “rolling” 10 year basis was compared.
Modeling Methodology
- “Hypothetical Issuance Coupon” T : The issuance coupon for the “hypothetical issuer” on each trading day “Hypothetical Issuance Coupon” T = (U.S. 10-Year Treasury RateT + U.S. 10-Year Corporate Generic BBB IndexT) Where T is any given market trading day
- “Portfolio Cost of Debt” T : Calculated as the average “Hypothetical Issuance Coupon” over a ten year time horizon given a selected portfolio structure “Portfolio Cost of Debt for Portfolio 1”T = (“Hypothetical Issuance Coupon”T + “Hypothetical Issuance Coupon”T+2years + “Hypothetical Issuance Coupon”T+4years + “Hypothetical Issuance Coupon”T+6years + “Hypothetical Issuance Coupon”T+8years) / 5 “Portfolio Cost of Debt for Portfolio 2”T = (“Hypothetical Issuance Coupon”T + “Hypothetical Issuance Coupon”T+1years + “Hypothetical Issuance Coupon”T+2years +…+ “Hypothetical Issuance Coupon”T+8years + “Hypothetical Issuance Coupon”T+9years) / 10 “Portfolio Cost of Debt for Portfolio 3”T = (“Hypothetical Issuance Coupon”T + “Hypothetical Issuance Coupon”T+3months + “Hypothetical Issuance Coupon”T+6months +…+ “Hypothetical Issuance Coupon”T+38months + “Hypothetical Issuance Coupon”T+39months) / 40 “Portfolio Cost of Debt for Portfolio 4”T = (“Hypothetical Issuance Coupon”T + “Hypothetical Issuance Coupon”T+1month + “Hypothetical Issuance Coupon”T+2months +…+ “Hypothetical Issuance Coupon”T+118months + “Hypothetical Issuance Coupon”T+119months) / 120 Where T is any given market trading day
Summary of Debt Issuance Strategies
| Portfolio 1 | Portfolio 2 | Portfolio 3 | Portfolio 4 | |
|---|---|---|---|---|
| Issuance Tenor | 10 year | 10 year | 10 year | 10 year |
| Strategy Horizon | 10 year (rolling) | 10 year (rolling) | 10 year (rolling) | 10 year (rolling) |
| Data Start Date | 2002-09-30 | 2002-09-30 | 2002-09-30 | 2002-09-30 |
| Data End Date | 2016-09-28 | 2016-09-28 | 2016-09-28 | 2016-09-28 |
| Credit Rating | BBB Generic | BBB Generic | BBB Generic | BBB Generic |
| Currency | USD | USD | USD | USD |
| Annual Issuance Size | $1,000,000,000 | $1,000,000,000 | $1,000,000,000 | $1,000,000,000 |
| Issuance Frequency (p.a.) | 0.5 | 1 | 4 | 12 |
| Size Per Issuance | $2,000,000,000 | $1,000,000,000 | $250,000,000 | $83,333,333 |
Analysis Outputs & Results
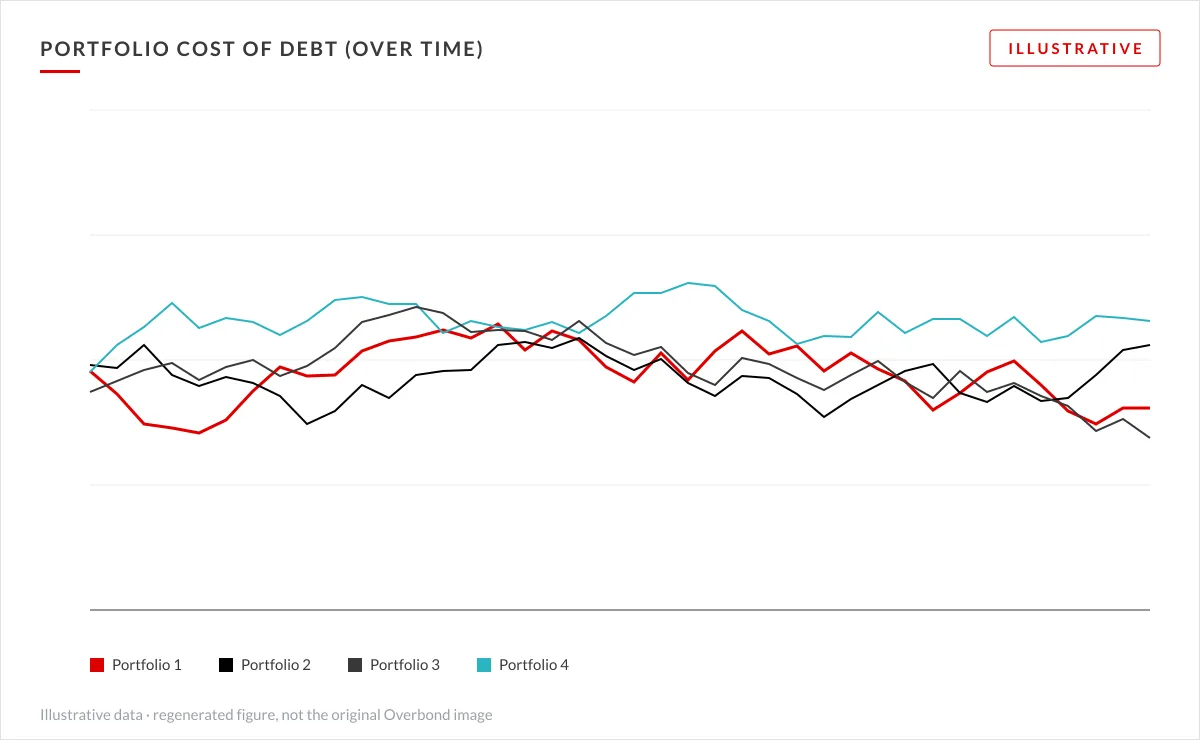
Our back-tested analysis demonstrates that an institution capable of issuing in greater frequency and in smaller issuance size could generate substantial cost of debt savings, while also reducing interest coupon volatility.
Mean Portfolio Cost of Debt
- The mean portfolio cost of debt for “Portfolio 4” (monthly issuance) is 22 bps per annum lower than “Portfolio 1” (bi-annual issuance)
- In dollar terms, this translates to ~$11 million in annual savings*
Median Portfolio Cost of Debt
- The median portfolio cost of debt for “Portfolio 4” (monthly issuance) is 14 bps per annum lower than “Portfolio 1” (bi-annual issuance)
- In dollar terms, this translates to ~$7 million in annual savings*
Standard Deviation of Portfolio Cost of Debt
- The standard deviation in portfolio cost of debt for “Portfolio 4” (monthly issuance) is 7 bps lower than “Portfolio 1” (bi-annual issuance)
Summary of Debt Issuance Strategies
| Portfolio 1 | Portfolio 2 | Portfolio 3 | Portfolio 4 | |
|---|---|---|---|---|
| Issuance Tenor | 10 year | 10 year | 10 year | 10 year |
| Strategy Horizon | 10 year (rolling) | 10 year (rolling) | 10 year (rolling) | 10 year (rolling) |
| Data Start Date | 2002-09-30 | 2002-09-30 | 2002-09-30 | 2002-09-30 |
| Data End Date | 2016-09-28 | 2016-09-28 | 2016-09-28 | 2016-09-28 |
| Credit Rating | BBB Generic | BBB Generic | BBB Generic | BBB Generic |
| Currency | USD | USD | USD | USD |
| Annual Issuance Size | $1,000,000,000 | $1,000,000,000 | $1,000,000,000 | $1,000,000,000 |
| Issuance Frequency (p.a.) | 0.5 | 1 | 4 | 12 |
| Size Per Issuance | $2,000,000,000 | $1,000,000,000 | $250,000,000 | $83,333,333 |
| Portfolio Cost of Debt | ||||
| Mean (%) | 5.59% | 5.46% | 5.38% | 5.37% |
| Median (%) | 5.54% | 5.47% | 5.40% | 5.40% |
| Maximum (%) (%) | 6.42% | 6.05% | 5.94% | 5.87% |
| Minimum (%) | 4.85% | 5.73% | 4.85% | 4.80% |
| Standard Deviation | 0.35% | 0.30% | 0.28% | 0.28% |
| Estimate Interest Expense (Assuming Average Notional Outstanding of $5 Billion)* | ||||
| Mean ($) Interest Expense | $279,500,000 | $273,000,000 | $269,000,000 | $268,500,000 |
| Median ($) Interest Expense | $277,000,000 | $273,500,000 | $270,000,000 | $270,000,000 |
Analysis Outputs & Results
Key analysis results below.
Portfolio Cost of Debt (Over Time)
Portfolio Cost of Debt: Mean
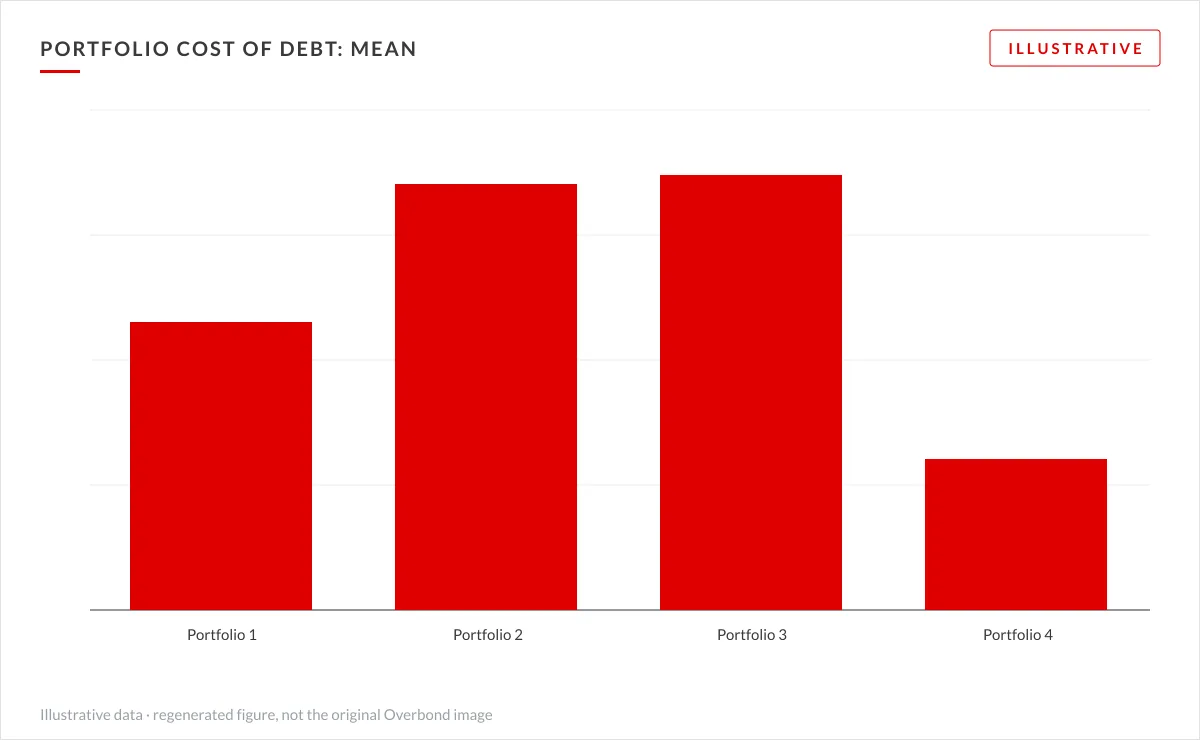
The mean portfolio cost of debt for “Portfolio 4” is 22 bps per annum lower than “Portfolio 1” In dollar terms, this translates to ~$11 million in annual savings
Portfolio Cost of Debt: Median
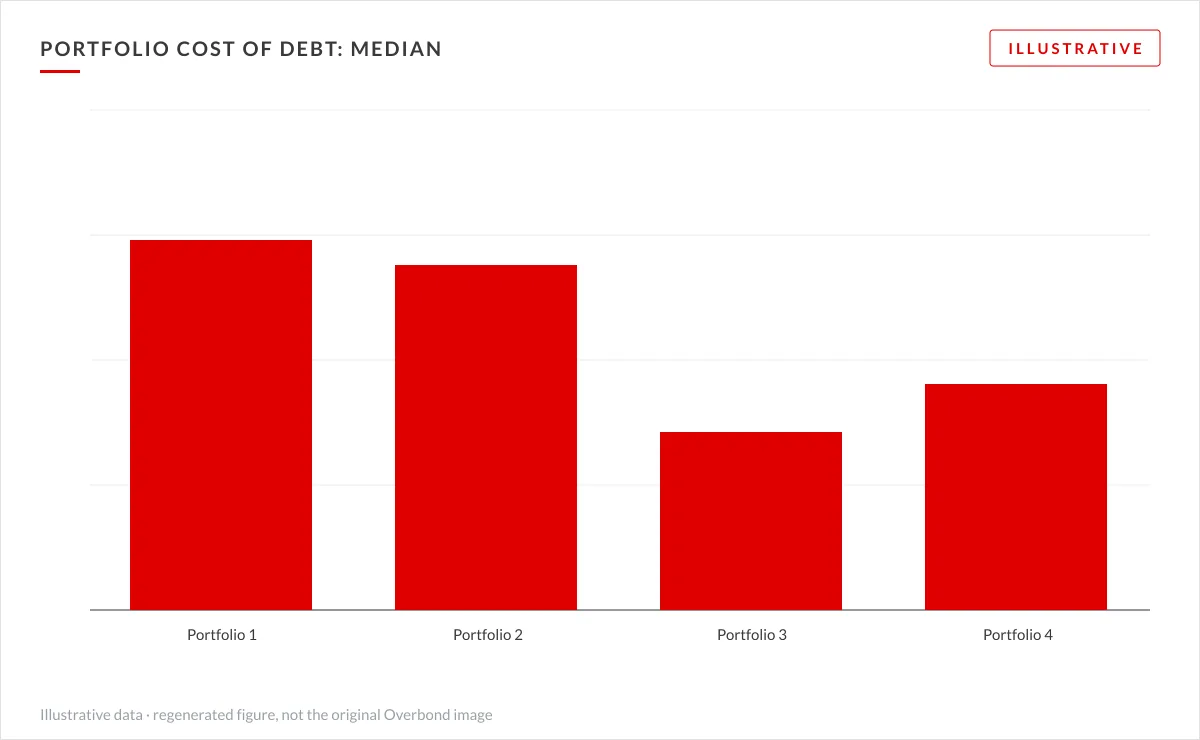
The median portfolio cost of debt for “Portfolio 4” is 14 bps per annum lower than “Portfolio 1” In dollar terms, this translates to ~$7 million in annual savings*
Portfolio Cost of Debt: Standard Deviation
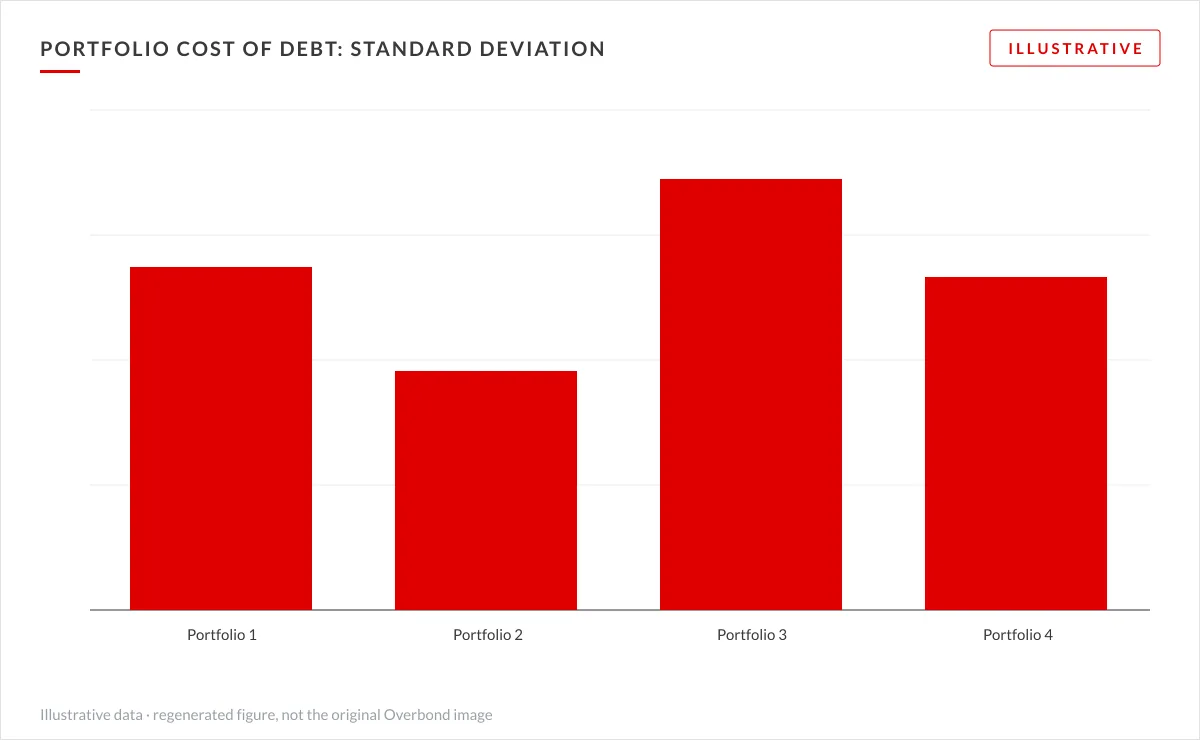
The standard deviation in portfolio cost of debt for “Portfolio 4” is 7 bps lower than “Portfolio 1”
Conclusions
- Issuing debt on a more frequent basis and in smaller issuance sizes has been shown to lower the average cost of debt
- The ability to issue on a more frequent basis and in smaller issuance sizes could be achieved through a less manually intensive primary bond issuance process. Fintech platforms such as Overbond reduce manual inputs and result in more attractive economics for both issuers and dealers
- The ability to issue on a more frequent basis and in smaller sizes could allow institutions to improve revenue-expense matching and/or asset-liability matching
- The ability to issue on a more frequent basis and in smaller issuance sizes could help issuers achieve a stronger understanding of debt capital markets
- The ability to issue with greater frequency could help issuers achieve a more diversified investor base – as investors would have many more opportunities to participate in new issues
Analysis Limitations
- Examined debt portfolios are composed of only 10-year tenor corporate bonds
- Only USD debt issuances from September 2002 to September 2016 were analyzed
- Legal expenses related to bond issuance were not included in the back testing analysis
About Overbond
Overbond brings all bond market participants together. It is a platform that makes primary bond issuance digital, transparent and secure. Overbond connects corporate and government issuers with dealers and investors directly.
Contact: Vuk Magdelinic | CEO +1 (416) 559-7101