M&A Financing With Bond Issuance Report
Overview
The report analyzed key considerations in financing M&As with bond issuance and evaluated multiple funding strategies from the perspective of a strategic corporate acquirer.
Abstract: Global M&A activity has been robust in recent years, fueling the growth of the acquisition finance market. Debt financing, in particular, has become increasingly common for M&A transactions, thanks to the record low interest rate environment. While bridge financing is often imperative for the success for an acquisition, acquirers are recommended to promptly contemplate long-term financing. In this report, we analyzed key considerations in issuing long-term debt securities into the capital markets:
- Transaction timing
- Interest rate exposure
- Credit spread volatility
- Issuance strategy comparison
- Execution risk mitigation
Ultimately, we aim to discover how an acquirer can best execute long-term financing through bond issuance.
Assumptions:
- The acquirer has decided to acquire the target at a price of $5bn
- The acquirer plans to finance 40% of the purchase price ($2bn) through long-term bond issuance
- The acquirer aims to have long-term financing in place within 6 months post acquisition announcement
- Currently, the acquirer has a credit rating of BBB
Transaction Timing
Executing an M&A transaction from announcement to closing can be a lengthy process that takes months to complete.
Days to Complete M&As (Year)
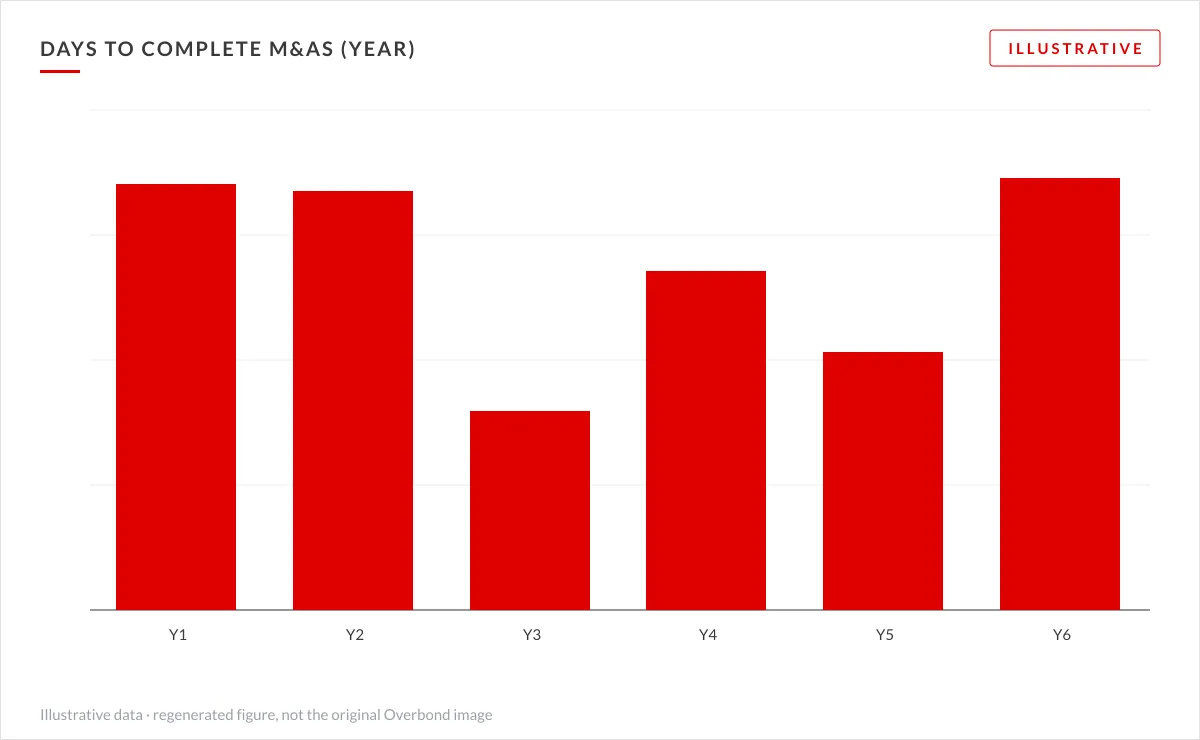
The average number of days to complete merger transactions (US$100mn+) is 94 days
Days to Complete M&As (Deal Size)
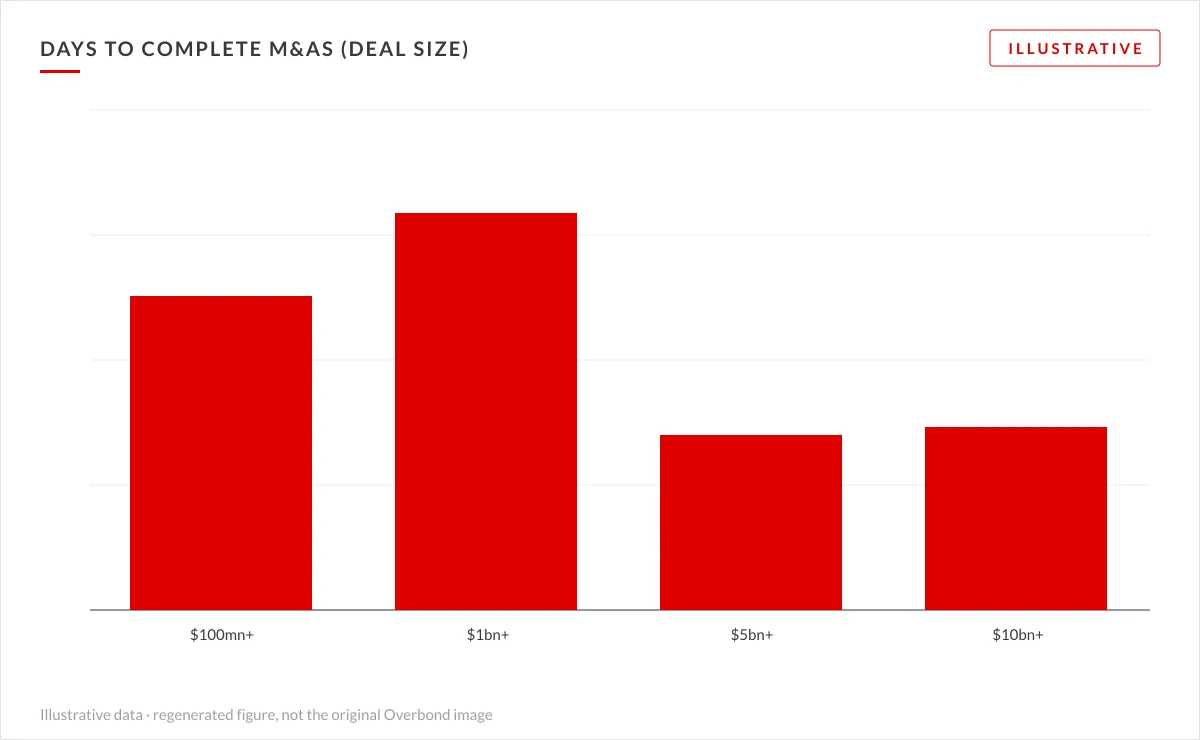
The average number of days to complete mega merger transactions (US$1,000mn+) is 138 days
Data Inputs: 161 completed corporate mergers (US$100mn+) announced from 2013 to 2016 (Source: Thomson Reuters)
Issuers should take into consideration external dependencies throughout the M&A transaction duration, as outlined below, when determining the time to issue a bond.
Indicative M&A Execution Timeline
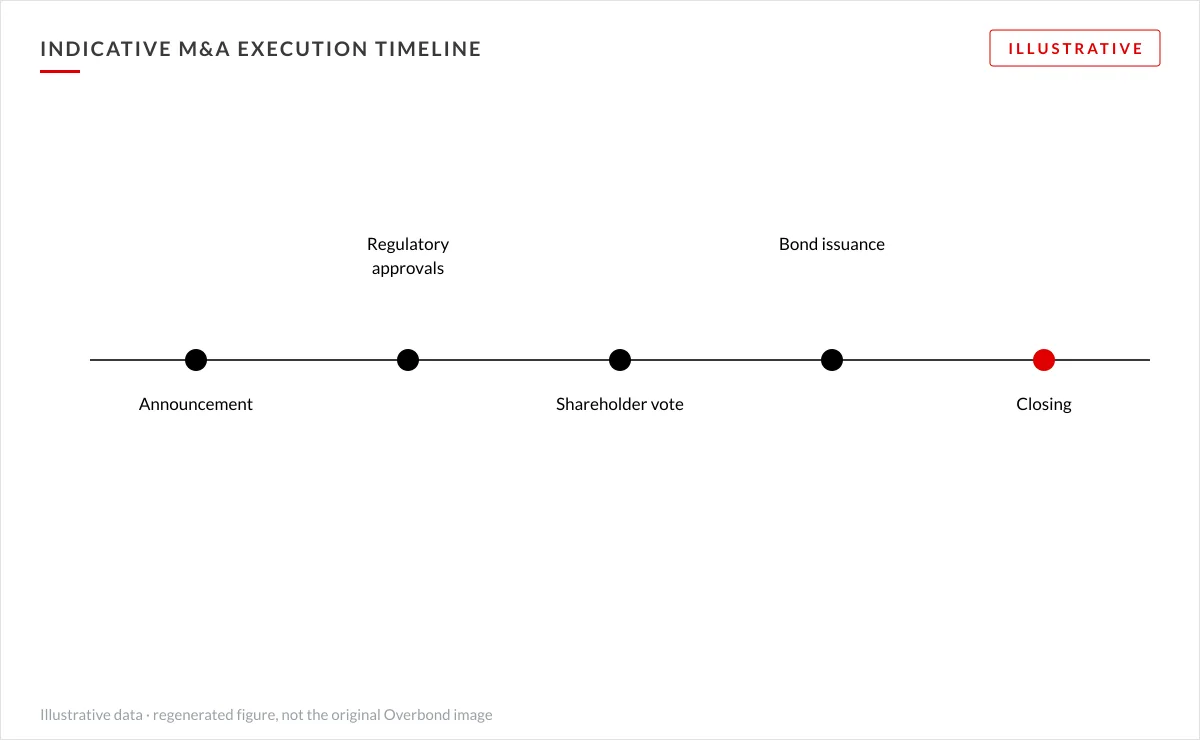
Assumption: Quarter end dates are March 31, June 30, September 30, December 31 and blackout period is 45 days post quarter end
Interest Rate Exposure
Given that M&A transactions often take more than 3 months to close, managing potential interest rate exposure inevitably becomes a top priority for issuers. Interest rate forecast and sensitivity analysis can help issuers optimize bond issuance strategy with respect to timing, term and hedging.
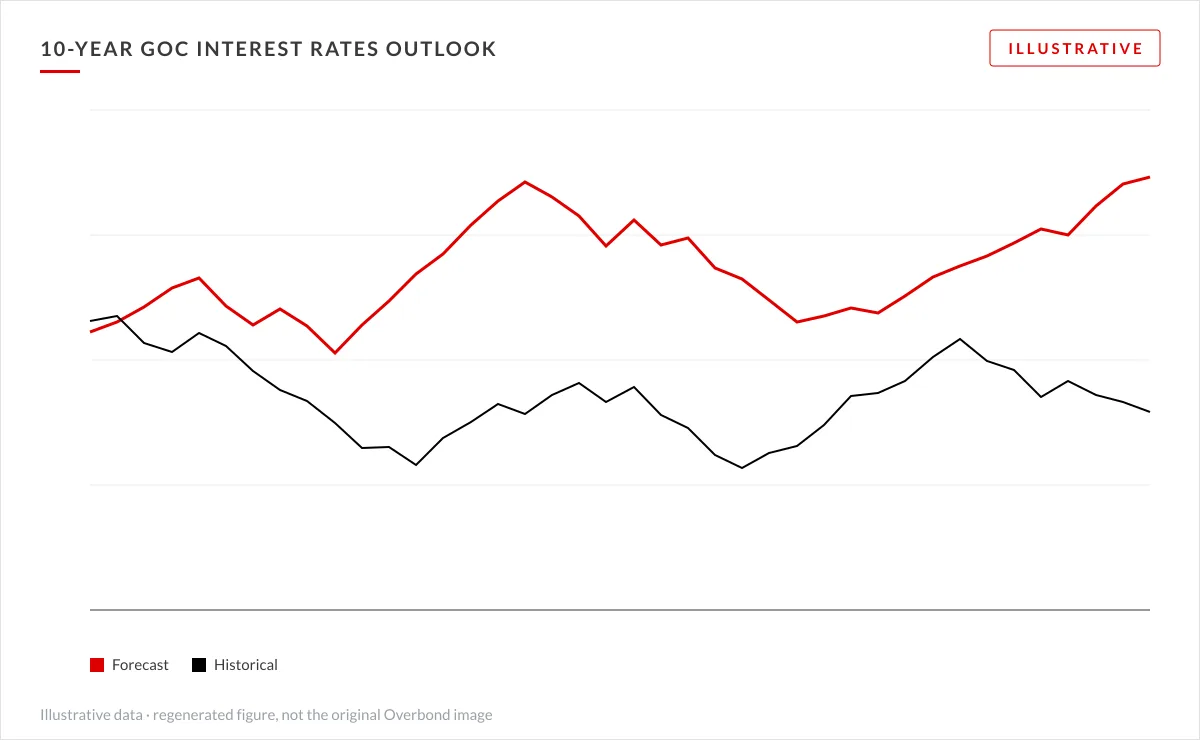
Analysis Results: Interest rates will likely rise steadily in the next 3 months. By the end of Q2, interest rates in the 10-year and 30-year tenors are forecasted to increase by 30 bps and 23 bps respectively, compared to current levels.
10-Year GoC Interest Rates Outlook
30-Year GoC Interest Rates Outlook
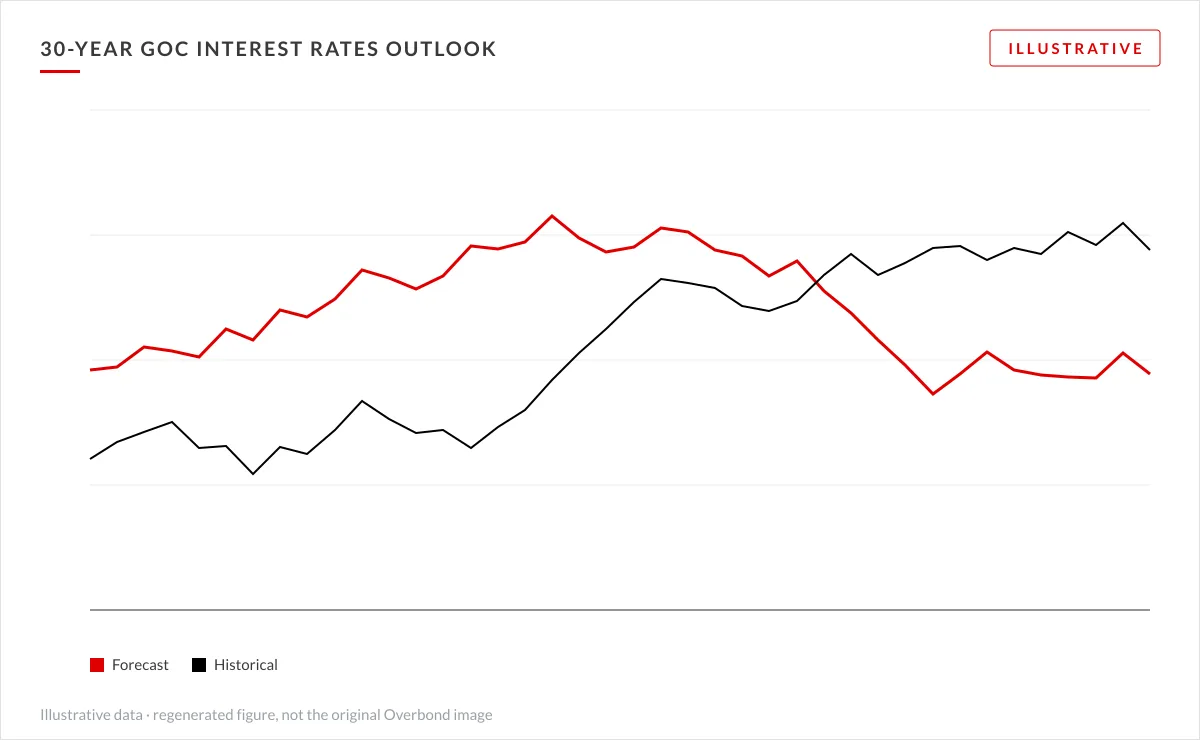
Data Inputs: Current market yield as of April 4, 2017 (Source: Thomson Reuters, Bloomberg).
Analysis Results: Interest rate movement, even by 5 bps, can result in millions of dollars of difference in total interest expense. For a 10-year $2bn bond issuance, an increase in interest rate by 5 bps translates to PV of additional interest cost of over $9.2mn.
Sensitivity Analysis – $2bn Bond Issuance
| 5-Year | 7-Year | 10-Year | 30-Year | |
|---|---|---|---|---|
| 5 BPS | ||||
| Annual Interest Cost | $1,000,000 | $1,000,000 | $1,000,000 | $1,000,000 |
| Total Interest Cost | $5,000,000 | $7,000,000 | $10,000,000 | $30,000,000 |
| Discount Rate 1 | 1.084% | 1.274% | 1.581% | 2.265% |
| PV of Total Interest Cost | $4,854,125 | $6,676,636 | $9,215,985 | $21,686,104 |
| PV of Total Interest Cost as % of Principal | 0.243% | 0.334% | 0.461% | 1.084% |
| 25 BPS | ||||
| Annual Interest Cost | $5,000,000 | $5,000,000 | $5,000,000 | $5,000,000 |
| Total Interest Cost | $25,000,000 | $35,000,000 | $50,000,000 | $150,000,000 |
| Discount Rate 1 | 1.084% | 1.274% | 1.581% | 2.265% |
| PV of Total Interest Cost | $24,270,627 | $33,383,179 | $46,079,924 | $108,430,522 |
| PV of Total Interest Cost as % of Principal | 1.214% | 1.669% | 2.304% | 5.422% |
1Discount rate: Underlying government bond yield as of April 4, 2017 (Source: Thomson Reuters)
Credit Spread Volatility
Besides rates, credit spread can be a major component of an issuer’s total cost of debt. Establishing an understanding of historical credit spread volatility is critical to the success of bond issuance.
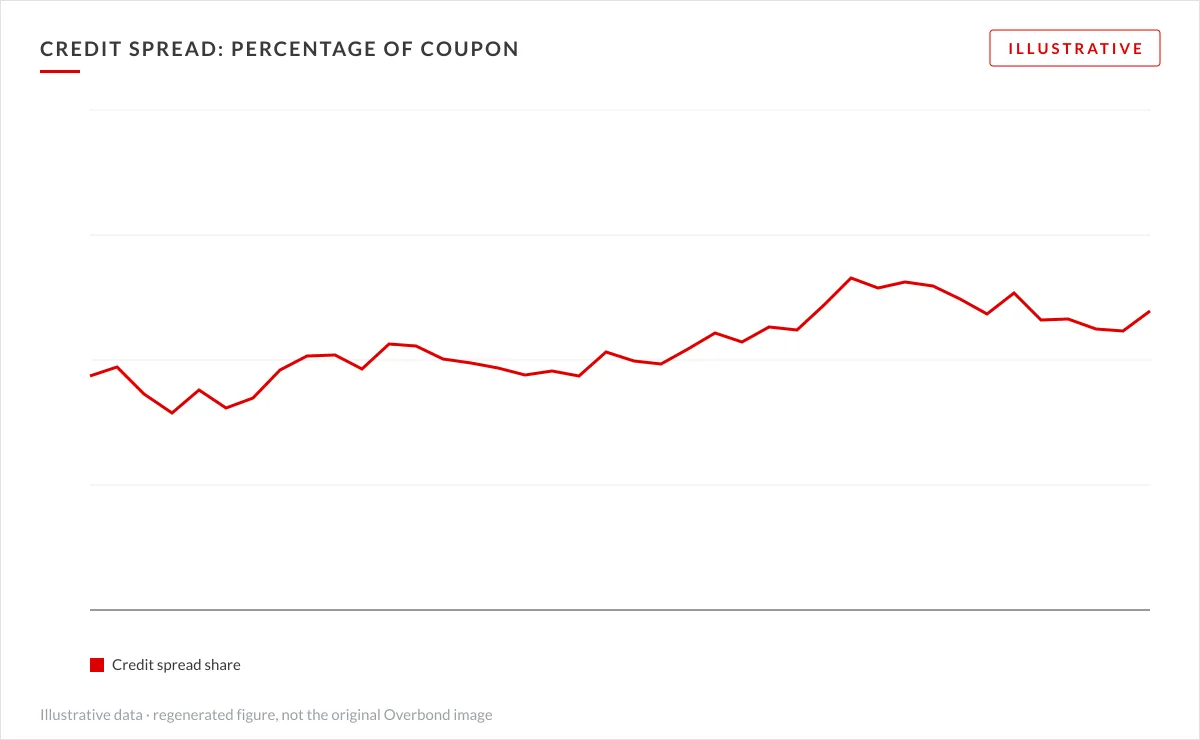
Analysis Results: Credit spread has accounted for over 50% of the cost of debt for a BBB-rated issuer since 2015, as demonstrated in the chart below.
Credit Spread: Percentage of Coupon
Analysis Results:
- The mean and standard deviation of 3-month spreads movement are 16.5 bps and 14.0 bps respectively (2013-2016).
- In the same period, the mean and standard deviation of 3-month rates movement are 26.5 bps and 19.5 bps respectively. This demonstrates that rates movement is larger and more volatile than spreads movement.
- The correlation coefficient between government bond yields and credit spreads is -0.77, indicating a strong negative correlation. In other words, government bond yields movement can be partially offset by credit spreads movement.
Credit Spread and Indicative Coupon
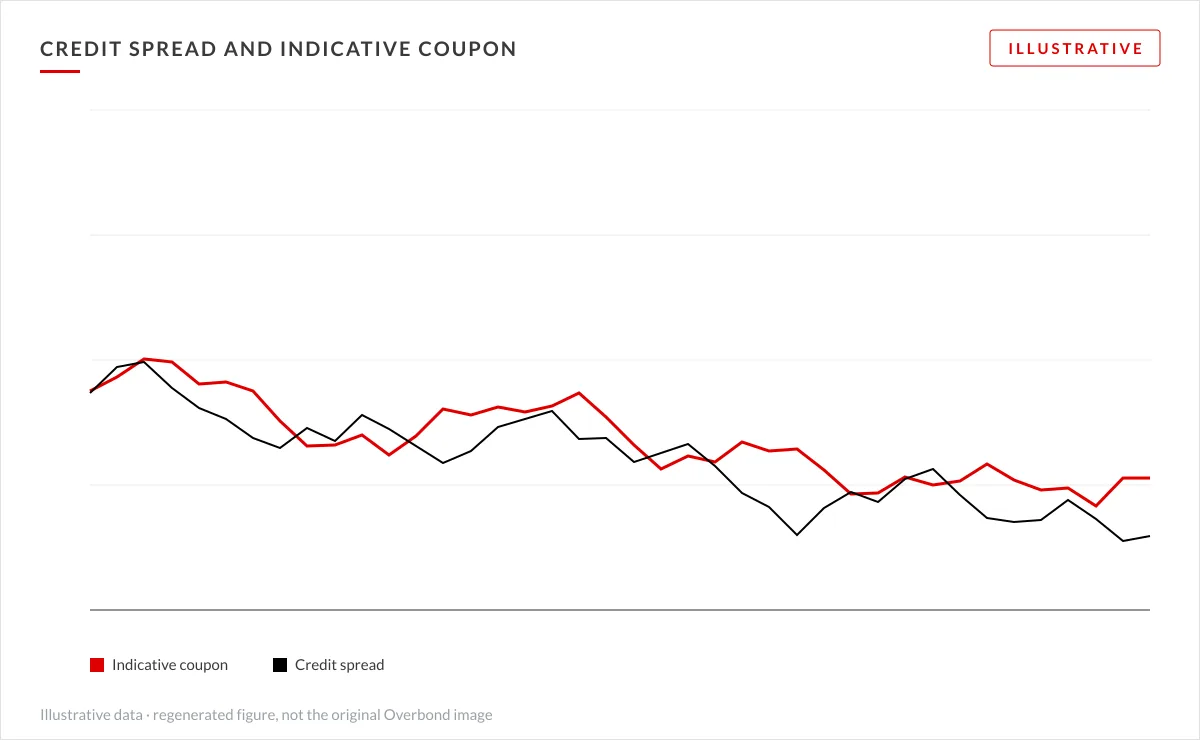
Data Inputs: 10-Year GoC Bond Yields and 10-Year Canadian Corporate Generic “BBB” Yields from 2013 to 2016. In aggregate, there are over 6,000 unique data points (Source: Public Data).
Issuance Strategy Comparison
Tasked with identifying the optimal issuance strategy, the acquirer’s treasury team is advised to assess the costs and benefits of multiple funding alternatives under different market conditions.
Analysis Results: Based on the table below, the option in the first column, issuing now to prefund the M&A will address multiple risks and hedging cost, while incurring cost of negative carry would continue.
Issuance Strategies – $2bn 10-Year Bond Issuance
| Issuance Strategy | Prefund by issuing now | Issue in 6 months without hedging | Hedge now and issue in 6 months |
|---|---|---|---|
| Cost of negative carry | Yes | None | None |
| Cost of hedging | None | None | Yes |
| Interest rate risk | None | Yes | None |
| Credit spread risk | None | Yes | Yes |
| Market capacity risk | None | Yes | Yes |
Analysis Results:
In a rising interest rate environment, issuing now likely leads to the lowest cost of funding; if rates decline or remain unchanged, issuing later without hedging is generally the most optimal strategy.
Scenario Analysis: Cost of Funding
| Execution Plan | Issue 10.5-year bond today | Issue 10-year bond in 6 months (no hedging) | Issue 10-year bond in 6 months (hedging) |
|---|---|---|---|
| Rates: +25 bps | 3.607% | 3.650% | 3.480% |
| Rates: unchanged | 3.607% | 3.400% | 3.480% |
| Rates: -25 bps | 3.607% | 3.150% | 3.480% |
| Incremental cost | 1. Negative carry: 15.7 bps/year 2. Extra 6-month: 5.0 bps/year Total: 20.7 bps/year | N/A | Hedging cost: 8.0 bps/year |
Data Inputs: 10-Year GoC Bond Yields and 10-Year Canadian Corporate Generic “BBB” Yields from 2013 to 2016. In aggregate, there are over 6,000 unique data points (Source: Public Data).
Execution Risk Mitigation
To mitigate overall execution risk, the acquirer’s treasury team is recommended to include special mandatory redemption provision in the prospectus.
Special Mandatory Redemption Provision: In recent years, most M&A-driven bond issues include some type of special mandatory redemption clauses, also known as escrow features, that require the issuer to redeem all outstanding bonds at a predetermined redemption price provided that the acquisition is not consummated prior to a predetermined redemption date:
- The escrow structure has proliferated among both U.S. issuers and Yankee bond issuers
- It is usually cost effective for the issuer to call the bond compared to the standard make whole provision, if the acquisition is terminated
- On May 6, 2016, Halliburton redeemed US$2.5bn notes at 101% when its merger with Baker Hughes was terminated
- Below is a select list of recent M&A-related bond transactions that include the escrow feature
| Date | Issuer | Size (US$ mn) | Tenor | Special Mandatory Redemption | Term to Redemption Date | Use of Proceeds |
|---|---|---|---|---|---|---|
| 04/04/2017 | Cenovus Energy | $2,900 | 10, 20, 30 | 101%+accrued & unpaid interest | 12 months | Acquisition of ConocoPhillips |
| 11/30/2016 | Ritchie Bros | $500 | 8 | 100%+accrued & unpaid interest | 11 months | Acquisition of IronPlanet Holdings Inc. |
| 06/28/2016 | Molson Coors | $5,300 | 3, 5, 10, 30 | 101%+accrued & unpaid interest | 4.5 months | Acquisition of SABMiller plc’s interest in MillerCoors LLC |
Execution Risk Mitigation (Cont’d)
Other factors that issuers should consider to mitigate execution risk include foreign markets issuance, staggering issuance, syndication selection, credit rating impact and regulatory requirements.
Accessing Offshore Bond Markets: The issuer can take advantage of tapping international bond markets for acquisition financing:
- An offshore debt offering can provide proceeds for a foreign target acquisition without currency risk
- It’s possible to take advantage of opportunistic funding levels in foreign markets and swap proceeds back
- Some international markets (i.e. U.S.) can offer a deeper liquidity pool than domestic bond market
- The issuer can diversify its investor base and access variety of financing structures unavailable at home
There are also some disadvantages associated with foreign bond issuance:
- Higher transaction costs including underwriting fees, legal fees, documentation etc.
- More time spent on roadshows as foreign investors need to become comfortable with the name and the story
- Additional hedging fees if the issuer swaps the foreign proceeds back to its local currency
Additional Considerations
- Staggering issuance: utilize this strategy to meet large funding requirement with multiple offerings while managing maturity profile and reducing execution risk
- Syndicate selection: a comprehensive review of dealers’ ongoing coverage, execution capabilities, role in M&A transaction and credit commitment
- Credit rating impact: promptly disclose all information required to help credit rating agencies make an informed decision
- Regulatory requirements: actively work with the legal counsel to ensure all aspects of the transaction are fully compliant
Conclusions
Key considerations in issuing bonds to fund M&A transactions have been discussed in the report. Below is a summary of our findings and conclusions:
- M&A-driven bond issuance has been growing at an unprecedented pace; acquirers are frequently turning to bond markets for long term financing at a favorable rate, especially for large M&A transactions
- M&A transaction execution can be a lengthy process and various external dependencies should be considered to ensure the optimal timing of bond offerings
- Interest rate outlook and sensitivity analysis are helpful in developing bond issuance strategy, particularly in terms of timing, tenor and hedging
- Interest rate movement tends to be larger and more volatile than credit spread movement
- There is a strong negative correlation between interest rate and credit spread, thereby providing a natural hedging to partially reduce interest rate risk
- Issuers can benefit from performing costbenefit analysis and scenario analysis for different issuance strategies
- Mitigating overall execution risk requires issuers to consider factors such as tapping international markets, incorporating special mandatory redemption provision and utilizing staggering issuance mechanism.
About Overbond
Overbond brings all bond market participants together. It is a platform that makes primary bond issuance digital, transparent and secure. Overbond connects corporate and government issuers with dealers and investors directly.
Contact: Vuk Magdelinic | CEO +1 (416) 559-7101